How Canadian industrial tenants can win at the table with institutional landlords.
For most of the past five years, industrial tenants in Canada primarily had one choice: Accept the offer. With tight vacancy drawing close to historic lows and an undersupplied development pipeline, landlords had little incentive to move. That’s no longer the case.
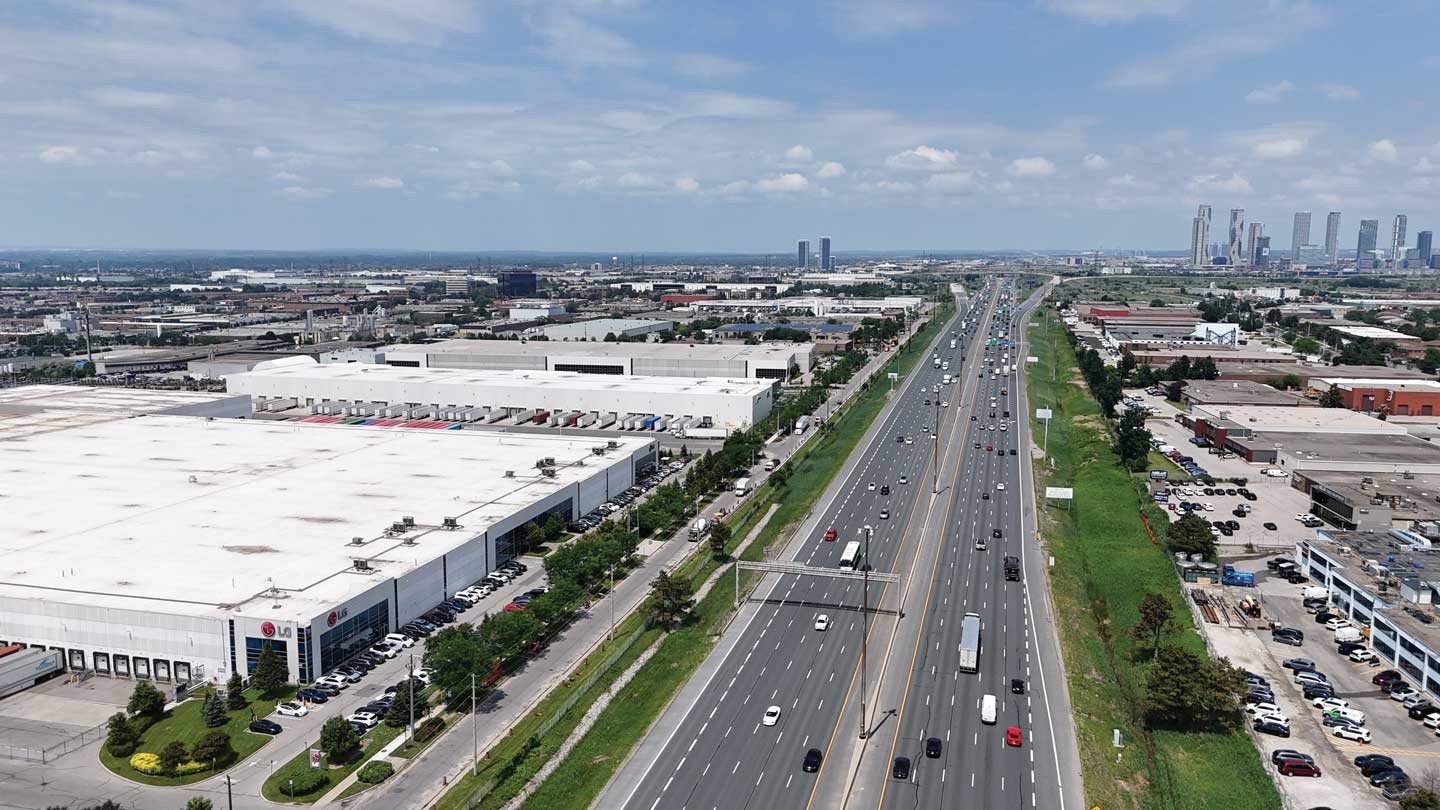
In the first quarter of the year, Canada’s industrial vacancy rate dipped for the first time since 2022, clocking in at around 3.5% as absorption ate into supply. The experience is not entirely uniform. Calgary and Edmonton are among the tightest markets in North America. Meanwhile, Montreal is still contending with structural oversupply, and the market is just beginning to stabilize in Vancouver and the Greater Toronto Area (GTA).
The net asking rates are illustrative. Vancouver, at around $19.50 Canadian to $20 Canadian per square foot net, is off its peak of $22 to $23. The GTA’s asking rate is in the mid-$16 range, with rates dipping to the low to mid teens in Durham, Hamilton and pockets of Mississauga, but climbing to the high teens for prime product in Northern GTA. Calgary fetches approximately $10.50 per square foot net, with tight small-bay vacancy. Montreal’s large-bay product, where oversupply is concentrated, is in the mid-$14s.
What makes this moment significant is not merely that rents have seen a dip. Institutional players, the biggest of all, now have an incentive to lease. BGO, Pure Industrial and Oxford Properties, among others, are offering free rent, tenant improvement allowances and other incentives to get deals done where there were no concessions available or required two years prior.
Institutional vs. Private: Why the Playbook Is Different
Negotiating with a landlord who owns the building versus negotiating with a committee that manages hundreds of buildings is not the same thing. The Canadian industrial market is anchored by giant institutional landlords that have asset management committees. Straightforward deals with institutional groups will take six to eight weeks to turn over.
When negotiating with institutional landlords, there is flexibility on tenant improvement and free rent packages to keep a face rate higher for investors. Private landlords, on the other hand, want to limit downtime and avoid writing a large up-front check. They are more open to bending on the face rate, as the asset is for cash flow and not necessarily for selling anytime soon. Once a tenant understands which kind of landlord they are engaging, the entire negotiation changes.
Understanding the Approval Process of Large Owners
Dealing with some of Canada’s biggest landlords (BGO, Pure Industrial, Concert Properties, Oxford Properties, Dream Industrial) requires an understanding of how they make internal decisions.
These are large organizations engaged in leasing, asset management and, depending on the asset’s size, review at the fund level. They are completely different from family owners that make leasing deals on conversation. Deals with large landlords typically take longer. For industrial spaces 100,000 square feet and above, tenants should expect to wait four to eight weeks between the time terms are agreed to and final sign-off, not including legal review. Deals can sometimes seem dead but are typically in the pipeline, meaning they will likely be executed over the next two months.
Experienced negotiators anticipate that these landlords need to meet specific objectives and will create their negotiation plan accordingly.
Retention Is a Lever if Tenants Know How to Use It
Landlords are mindful that re-leasing vacated spaces entails fresh leasing costs and capital expenditure and introduces an unexpected gap in fund distributions. Few tenants use this reality to their advantage. The same principles that guide fresh leasing negotiations also apply to renewals.
Many tenants simply check the renewal box. They do not expose the landlord’s fear of vacancy, thinking that it will be a disruption to their operating business if they do. However, a landlord’s fear of vacancy can translate into large figures being negotiated into tenants’ leases in the form of free rent or building efficiency upgrades.
Tenants should begin renewal discussions 12 to 18 months ahead of expiry. Depending on market conditions, this creates an opportunity to expose market availability that the landlord, operating on the assumption that a tenant will choose a simplistic renewal, lacks. Tenants who use time to their advantage are the biggest winners. Those that wait until six months before expiry have already given up most of the leverage they had in negotiations.
The Window Is Already Closing
Tight market conditions in Canada are attributable to heavy supply, but that is running its course. In 2025, industrial completions plummeted by 38.8% year over year — the worst mark in nearly five years — totaling just 23.4 million square feet nationally. Completions are forecast to decline even further in 2026 to roughly 20 million square feet, a level unseen in eight years.
Of the 24.8 million square feet of total industrial space under construction in Canada as of July, 54.6% is preleased (in Calgary, 84.8% of the pipeline is preleased). Both the Vancouver and Toronto markets just exited stabilization in the first quarter of the year. The only national exception of note is Montreal’s continued state of negative absorption, where tenants requiring large-bay spaces remain empowered, but that scenario may shift if no further new starts materialize.
Tenants weighing options on space from a 2027 to 2028 expiry timeline should be starting conversations now. Otherwise, they might find landlords in a different position when dealing with them in tighter markets.
Michael Law is managing partner at Lennard Commercial Realty in Toronto, where he specializes in industrial tenant representation and lease negotiation across Canada’s major markets. He can be reached at mlawrealestate.com.
Negotiation Levers and How to Pull ThemThe current negotiating environment offers more tools for tenants than it has in years; the challenge is deploying them strategically. The following examples reflect recent Greater Toronto Area market deals. Free rent: In the range of two to six months, extending up to 12 months upon committing to a larger square footage footprint on longer-term deals. Tenant improvement allowances: Expect substantial tenant improvement packages coupled with free rent from major landlords for the purposes of preserving a market face rate. Stepped rent structures: Landlords will entertain stepped rent structures that begin below today’s headline market rate and escalate each year. They protect the tenant from the risk of locking in today’s rate as a floor and typically do not have the same impact on a landlord’s fund-level yield. Timing: Getting negotiation talks underway 18 months out from expiry is a prerequisite for achieving the greatest success for tenants. Landlords hold the cards if tenants wait to approach them six months from expiry. |